CU80 Conviction and Car Insurance: What It Means for Your Cover
A CU80 conviction does not automatically stop you from getting car insurance. However, it can affect the insurers willing to cover you, the terms they offer and the price you pay.
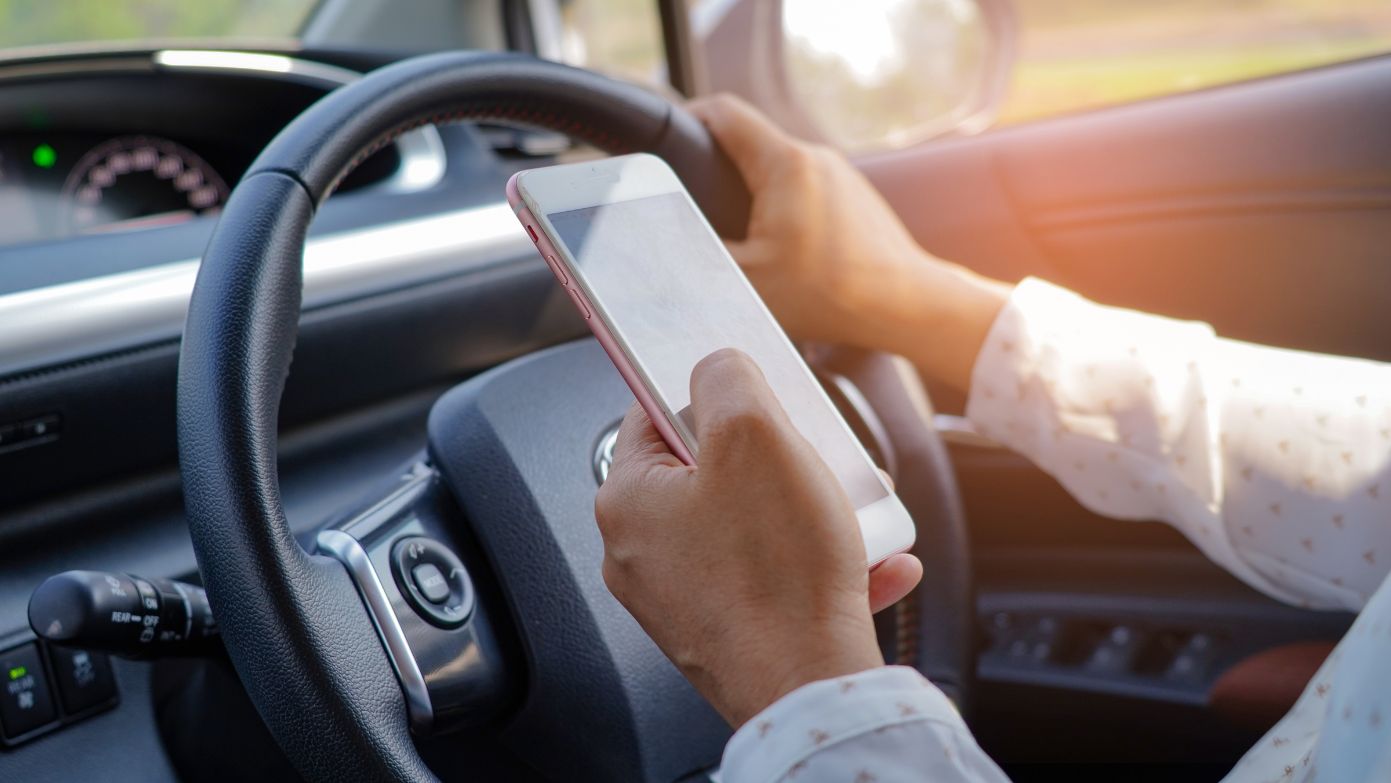
CU80 is an endorsement code linked to a breach of the rules on keeping proper control of a vehicle. It is commonly associated with using a mobile phone while driving.
At Got You Covered, we specialise in convicted driver insurance. If you have a CU80 on your driving record, we may be able to look for suitable cover through our panel of insurers, depending on your circumstances and the insurer’s criteria.
What does a CU80 conviction mean?
People often refer to a “CU80 conviction”, but CU80 is formally an endorsement code recorded against a driving licence.
The official CU80 description is “Breach of requirements as to control of the vehicle, such as using a mobile phone”.
CU80 is one of the construction and use offence codes and carries three to six penalty points.
Although mobile phone use is commonly associated with CU80, the code is broader than phone offences alone.
It is illegal to hold and use a phone, sat nav, tablet or another device that can send or receive data while driving. This applies whether the device is online or offline. It also applies when you are stopped at traffic lights, queuing in traffic or supervising a learner driver.
Hands-free devices can be used provided you do not hold them while using them. You must also remain in full control of the vehicle.
What are the penalties for a CU80?
A CU80 endorsement can carry three to six penalty points, depending on the offence.
For holding and using a phone, sat nav, tablet or similar device while driving, the standard penalty is six penalty points and a £200 fine.
If the case goes to court, you could also be disqualified from driving and receive a fine of up to £1,000. The maximum fine is £2,500 if you were driving a lorry or bus.
Penalty points can have wider consequences. Building up 12 or more penalty points within three years can lead to a driving disqualification.
What happens if you are a new driver?
A CU80 can be particularly significant for new drivers.
Your licence will be revoked if you receive six or more penalty points within two years of passing your first driving test.
Because a handheld mobile phone offence normally carries six points, one offence could be enough to trigger this rule.
If your licence is revoked, you will normally need to apply for a new provisional licence and pass your theory and practical tests again before getting a full licence.
How long does a CU80 stay on your driving record?
A CU80 endorsement stays on your driving record for four years from the date of the offence in Great Britain.
The time an endorsement remains on your driving record is not necessarily the same as the period before a related criminal conviction becomes spent. These are separate matters.
Our insurance glossary has more information about common insurance and motoring conviction terms.
Can you get car insurance with a CU80?
Yes. In many cases, you can still get car insurance with a CU80.
However, a motoring conviction can affect how an insurer assesses your circumstances. Some insurers may not offer a quote, while others may offer cover with a different premium, excess or policy terms.
The effect can depend on factors including:
- how recent the CU80 is
- how many penalty points you have
- whether you have other convictions
- your claims history
- your age and driving experience
- the vehicle you drive
- how the vehicle is used.
At Got You Covered, we work with insurers that consider a range of driving histories. Our convicted driver insurance may therefore be an option if a CU80 is making standard insurance harder to find.
If you need cover for a van, we can also look at van insurance, subject to your circumstances and insurer criteria.
What if your CU80 led to a driving ban?
If your offence resulted in a driving disqualification, the insurance discussed here applies after the ban has ended and once your licence has been properly restored.
If you were disqualified for 56 days or more, you must apply for a new driving licence before driving again.
In some cases, a court may also require you to retake your driving test or complete an extended test.
How can a CU80 affect your car insurance premium?
There is no fixed amount that a CU80 will add to your insurance.
Insurers use their own underwriting rules to assess risk and set an insurance premium.
A recent CU80 could result in a higher premium, different excess or other policy conditions. However, your conviction is only one part of the calculation.
Insurers may also consider your age, claims history, vehicle, postcode, mileage, occupation, vehicle use and no-claims bonus.
You can read more about what affects your car insurance premium.
A CU80 does not automatically remove an existing no-claims bonus because this is mainly linked to your claims record. However, a conviction can still affect the overall price you are offered.
Do you need to tell your insurer about a CU80?
When buying or renewing insurance, answer the questions you are asked accurately.
An insurer or broker may ask for your offence code, offence date, number of penalty points and details of any disqualification. You may also be asked about other convictions, claims and drivers on the policy.
Consumers are expected to take reasonable care when answering an insurer’s questions.
Incorrect or incomplete information can affect your policy. Depending on the circumstances, an insurer could change the premium or terms, reduce a claim or take other action permitted by the relevant rules.
If you receive a CU80 during an existing policy, check your policy documents. The requirements for reporting changes during the policy term can vary.
What happens when a conviction becomes spent?
Spent status is separate from how long a CU80 remains visible on your driving record.
Where an offence resulted in a criminal conviction, when it becomes spent will depend on the relevant rehabilitation period.
When applying for insurance, you do not have to tell an insurance company about spent convictions.
This is why it is important to distinguish between the endorsement period on your driving record and the separate rules covering spent convictions.
What should you have ready for a CU80 insurance quote?
Having accurate information ready can make the quote process easier.
You may need:
- your driving licence details
- your CU80 offence date and penalty points
- details of other motoring convictions
- details of any previous driving ban
- your claims and accident history
- your no-claims bonus
- your vehicle registration
- your estimated annual mileage
- details of vehicle use and named drivers.
If you were previously disqualified, make sure your ban has ended and your licence has been properly restored before returning to driving.
Getting car insurance after a CU80 with Got You Covered
Having a CU80 does not necessarily mean you are out of insurance options.
At Got You Covered, we specialise in helping drivers whose circumstances can make standard cover harder to find. This includes drivers with motoring convictions, previous claims and a low or zero no-claims bonus.
We can take your CU80 and wider driving history into account and look for suitable options through our panel of insurers. Availability, price and policy terms will depend on your full circumstances and the insurer’s underwriting criteria.
If you are finding it difficult to get car or van insurance after a CU80, contact Got You Covered to see what cover may be available.
CU80 conviction and insurance FAQs
Is CU80 always a mobile phone offence?
No. CU80 covers a breach of requirements relating to control of a vehicle, with mobile phone use given as an example. It can therefore cover other control-related offences.
How many points do you get for a CU80?
CU80 carries between three and six penalty points. Holding and using a mobile phone or similar data device while driving normally carries six points and a £200 fine.
How long does a CU80 stay on your driving record?
A CU80 stays on your driving record for four years from the date of the offence in Great Britain.
Can you still get car insurance with a CU80?
Yes, in many cases. However, some insurers may not offer cover or may apply different premiums, excesses or terms. At Got You Covered, we may be able to look for cover through insurers that consider drivers with motoring convictions.
Will a CU80 make car insurance more expensive?
It can, but there is no fixed increase. Insurers assess the CU80 alongside your wider driving history, claims, vehicle, mileage, no-claims bonus and other rating factors.
Can insurance become cheaper as a CU80 gets older?
Possibly. Some insurers may treat an older CU80 differently from a recent offence. However, there is no guarantee that your premium will fall because your price will still depend on your circumstances and the insurer’s underwriting rules.
Our latest articles.
The latest news and advice from our industry experts.